Tennessee Car Loan Laws
Tennessee leaves the finance charge on a dealer credit sale largely to the contract, requires doc fees to be itemized, and allows repossession without a court order after default.
Updated By Lenditia Editorial Team 6-minute read No right to cure
In short
Tennessee's usury law does not treat the time-price differential on a dealer credit sale as interest, and its Retail Installment Sales Act excludes motor vehicles, so there is no general rate ceiling on a dealer car contract. Lenders registered as industrial loan and thrift companies may charge up to 36% on loans of $100 or more since July 1, 2025. Dealers may charge a doc fee with no dollar cap if they itemize it. Sales tax is 7% of the price minus your trade-in, plus local and single-article taxes on the first $3,200. There is no right to cure before repossession.
- Right to cure
- None in state law
- Rate ceiling
- No general cap on dealers
- Doc fee limit
- No cap; must be itemized
- Vehicle sales tax
- 7% + local on first $1,600
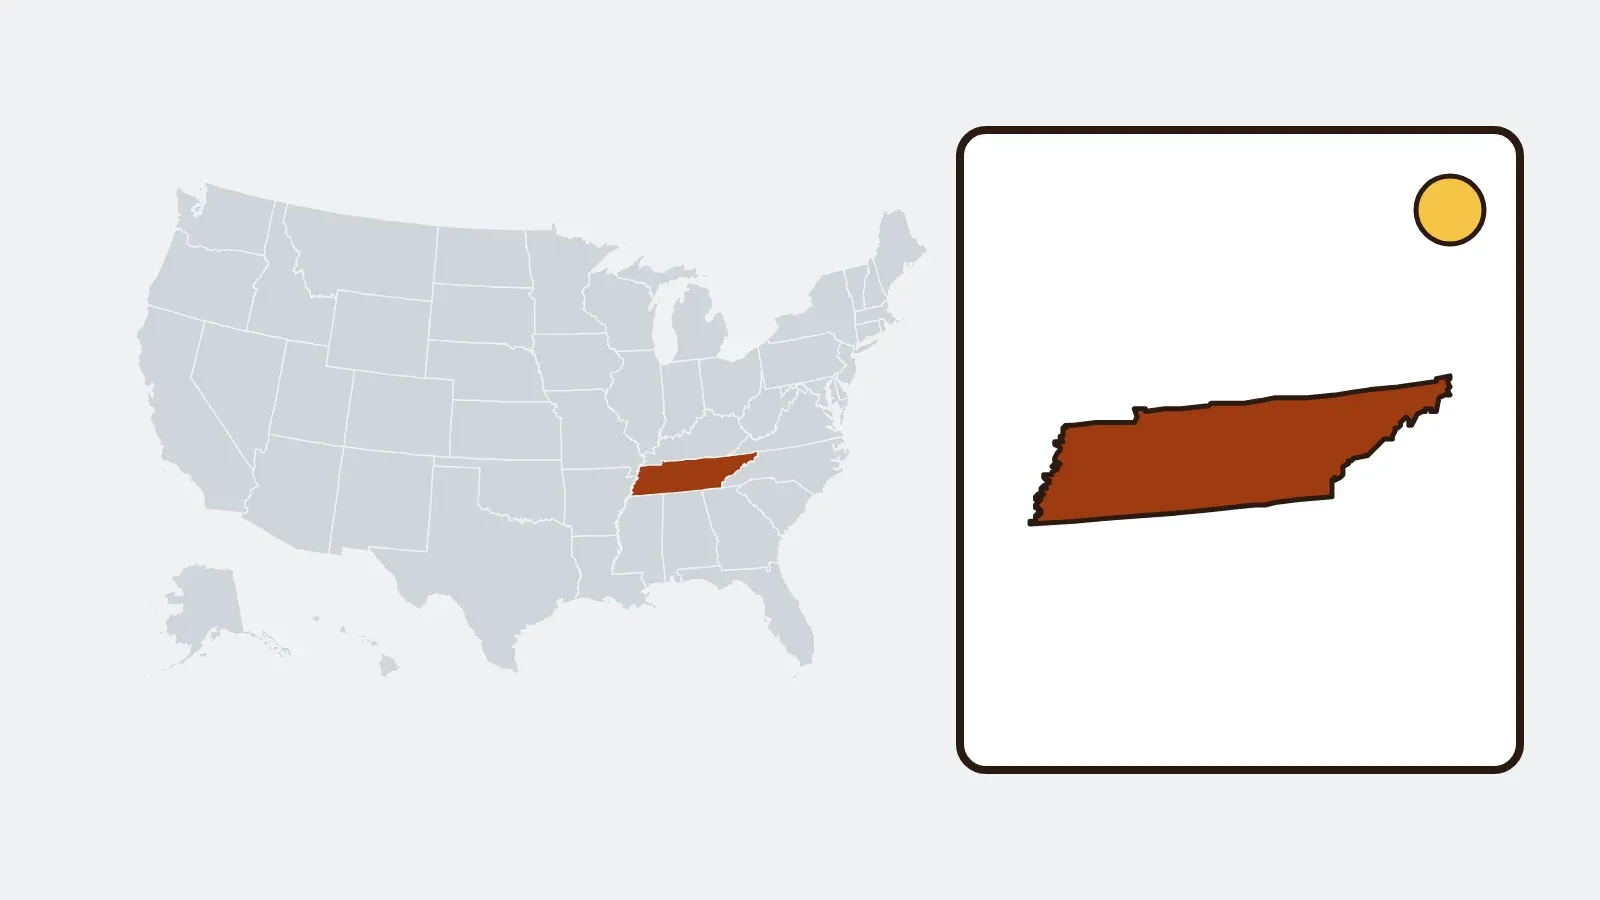
Tennessee car-finance rules at a glance
- Right to cure
- None in state law; repossession may follow a default under the contract
- Rate ceiling
- No general cap on dealer contracts; industrial loan and thrift loans up to 36%
- Time-price differentials are not interest (§47-14-102); the 36% limit took effect July 1, 2025.
- Doc fee limit
- No cap in state law; must be itemized and disclosed (§55-17-114)
- After repossession
- Notice before sale; right to redeem; deficiency allowed
- Vehicle sales tax
- 7% of price minus trade-in, plus local tax on first $1,600 and 2.75% on next $1,600
- Regulator
- Tennessee Department of Financial Institutions
Interest limits on Tennessee car financing
Tennessee splits car financing into two legal kinds. When a dealer sells you a car on credit, the extra you pay for buying over time is a time-price differential. Tennessee's general interest statute, Title 47, Chapter 14, says interest does not include time-price differentials (§47-14-102). The Retail Installment Sales Act, which caps charges on many consumer goods, leaves motor vehicles out of its definition of goods (§47-11-102). We found no other statute setting a general ceiling on dealer car contracts.
A direct loan is different. Industrial loan and thrift companies, which register with the Department of Financial Institutions, may charge an effective rate of up to 36% a year on closed-end loans of $100 or more. That limit took effect July 1, 2025, under Senate Bill 694, and applies to contracts made, amended or renewed on or after that date. Banks and credit unions follow their own rules.
Doc fees and sales tax in Tennessee
- Documentary fee. Dealers may charge a document preparation, processing or servicing fee on top of the price (§55-17-114). The law sets no dollar cap, but the amount must be stated separately and disclosed clearly before you sign.
- Not a government fee. A dealer may not tell you the doc fee is required by, or paid to, a government agency.
- State sales tax. The rate is 7% (§67-6-202).
- Trade-in. Tax is paid on the net difference: the price of the car minus the credit for the vehicle you trade in (§67-6-510).
| Tax | Rate | Part of the price it applies to |
|---|---|---|
| Local option tax | Up to 2.75%, set locally | First $1,600 |
| State single-article tax | 2.75% | $1,600.01 to $3,200 |
Add these taxes, the doc fee and any optional add-ons in the out-the-door price calculator before you agree to a monthly payment.
Falling behind and repossession in Tennessee
We found no Tennessee statute that gives car buyers a notice and a cure period before repossession. Your contract defines default, and once you are in default the lender may use Tennessee's version of Article 9 of the Uniform Commercial Code, in Title 47, Chapter 9.
- Repossession. The lender may take the car without a court order only if it avoids a breach of the peace (§47-9-609).
- Notice before sale. Article 9 requires the lender to notify you before it sells the car, so you know when and how the sale will happen.
- Redemption. Until the sale, you may get the car back by paying what the law requires, which is usually the full balance plus costs.
- Deficiency. If the sale brings less than you owe, you can be held liable for the rest; if it brings more, the surplus belongs to you.
Our guides to repossession and the balance left after a sale cover each step. If you are on active military duty, the federal Servicemembers Civil Relief Act can require a court order before repossession.
Where to check a lender and complain
The Department of Financial Institutions registers industrial loan and thrift companies, a common type of non-bank consumer lender. Dealers answer to the state's motor vehicle dealer laws, and banks and credit unions to their own regulators. For title pledge and payday rules, see Lendmira's Tennessee page.
Tennessee Department of Financial Institutions
Registers industrial loan and thrift companies and oversees the rates they may charge.
Tennessee Attorney General
Its consumer protection division handles complaints about deceptive dealer practices.
Consumer Financial Protection Bureau
Takes complaints about auto lenders and servicers, including banks and finance companies.
Questions people ask
Is there a maximum interest rate on a car loan in Tennessee?
Not a general one for dealer credit sales: the time-price differential is not treated as interest. Industrial loan and thrift companies may charge up to 36% a year on loans of $100 or more.
How much can a Tennessee dealer charge for a doc fee?
There is no dollar cap. The fee must be listed separately and disclosed clearly before you sign, and the dealer may not present it as a government fee.
How is sales tax figured on a car in Tennessee?
7% state tax on the price minus your trade-in, plus a local tax of up to 2.75% on the first $1,600 and a 2.75% state single-article tax on the part from $1,600.01 to $3,200.
Do I get a warning before repossession in Tennessee?
State law does not require one. The lender must avoid a breach of the peace and notify you before it sells the car. See what to do when you fall behind.
Sources
- Tennessee Code §47-14-102: Interest rate definitions, excluding time-price differentials (2024)
- Tennessee Code §47-11-102: Retail Installment Sales Act definitions (2025)
- Tennessee Senate Bill 694: Industrial loan and thrift rates, effective July 1, 2025
- Tennessee Code §55-17-114: Dealer fees and disclosures (2025)
- Tennessee Code §67-6-202 and §67-6-702: Sales tax rate and local option tax (2025)
- Tennessee Code §67-6-510: Tax on trade-ins (2024)
- Tennessee Code §47-9-609: Repossession after default (2024)
- Tennessee Department of Financial Institutions
Facts on this page were checked against these sources on October 26, 2026. Local option tax rates vary by city and county.
Read next
-
Guide
Retail installment contract
The disclosure box, the Holder Rule notice, spot delivery and arbitration clauses, and a signing checklist.
-
Guide
Out-the-door price
Every line from vehicle price to amount financed: doc fees, sales tax, add-ons and the trade-in.
-
Help
Repossession
When the lender can take the car, what an agent may not do, and how to get it back.